Jerry_Atrick
-
Posts
8,917 -
Joined
-
Last visited
-
Days Won
82
Content Type
Profiles
Forums
Gallery
Downloads
Blogs
Events
Our Shop
Movies
Everything posted by Jerry_Atrick
-
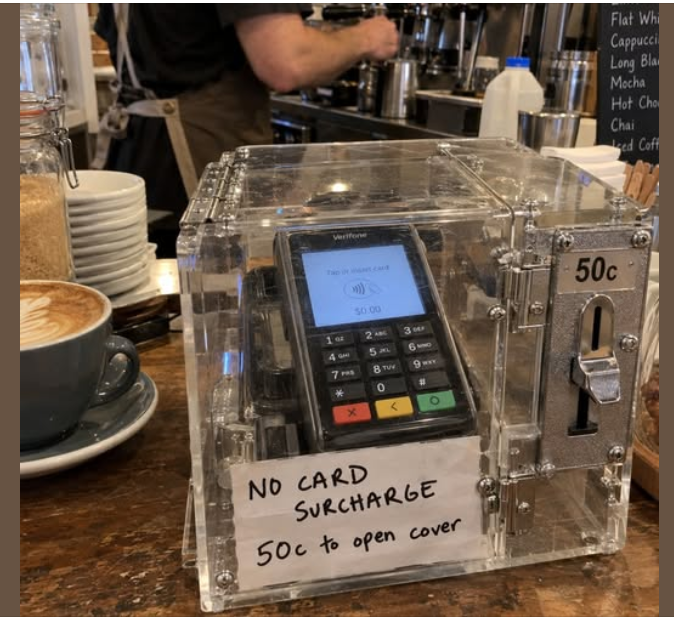
I agree with most of your post.. and I agree that those who need to roll over credit every month are susceptible to failure. After all, the stats for new startups is never great. But there are two things to point out. First, those businesses that are needing to use it every time and liable to fail, probably do within 12 months. They will use all credit available to them. The banks aggregate your credit risk across all known forms you can have. If you have a mortgage, a credit card, a car loan, a personal loan, are the director is person of control in a private company that has a company loan and company credit card, chances are they know about all of them them and they aggregate them to give a credit risk profile. So chances are, if you're in stress, they will know. And then, if you default on one of those loans, you default on all of them - that is under the BASEL rules (2.1 to be precise), which Australia has incorporated in its law. So if you are making out your credit cards, chances are the house of cards will come falling down fast. My point is, if you are constantly relying on the most expensive form of debt to keep you afloat, you are only prolonging the inevitable a short period of time. However, how many of the businesses may (and I stress, may) be using it for the occasional - or even frequent, but not financially punitive cash flow management. For example, you may have a bunch of clients that are poor payers.. As BAS accrues generally in the period the sale was made and not the cash was taken, you would be simply waiting for payment )yes, there are exemptions to allow payment of BAS in the period payment is collected, but that is by far the exception). So, to cover the BAS and prevent punitive penalties, you resort to a credit card. I imagine a fair share of those that avail themselves to their credit cards are in this or some other bucket that doesn't mean they are about to go to the wall. There are over 2.5 million small/medium businesses in Australia at last count; there is ample room for the temporary cover versus go under businesses. Until we know the stats, jumping to the conclusion that all, or even a vast majority are about to go to the wall is just that.. jumping to a conclusion. But that is thread drift. The thread is about government decisions and unintended consequences. What no one has picked up on is the fact that the "removal of credit card surcharges" is likely to mean that everyone pays for it whether or not they use a credit card.. and that it hides information from the consumer to give them a choice (or accept it). If I were a coffee shop owner, I may think I don't have the spare margin to absorb this. So, I would look at my sales of both credit and non credit cards; average them out and then apply the addition across all of them.. and the non credit card consumer subsidises the credit card user because I would want to keep my price increases as small as possible. I would say that can become an unintended consequence - mainly because those in the position to make the decision have probably not thought about it.
-
TBH, I am not sure I know what this means. Do I expect them to mind read? Of course not. I expect them to think. And of course, the ATO's operations are largely independent, but they do speak with their minister - it would be preposterous to say they wouldn't. Especially when a pre-implemented initiative is launched - there is usually a consultation period or some time before its implementation to give people time to adjust. Are you telling me the ATO wouldn't have said some time since its announcement and implementation - when they were preparing to pull the credit card payments - that they wouldn't have had a word. If that is the case and they knew it was going to impact a lot of businesses, then I would say that is incompetence of the ATO. Just to quote myself: A little sarcasm, I will admit, but I will put it simply: I get that Jim Chalmers wouldn't have consulted the ATO as he probably wasn't aware of the significance of credit card payments on taxation payments. I would be very surprised given the potential implications, they ATO didn't have a whisper in his hear.. and I am betting they put it like "well, we will lose xbn, so we will scrap it", not to say there will be a big impact to small business, because let's face it, they care little about it. Australia;s AAA rating has been around by at least one ratings agency (there are three big ones) since 2002 and across all 3 since 2011. And I am sure we agree there has been some pretty crap economic management in that period. So,. I am not sure what that bit has to add to the context. This is probably more down to Australia's resources boom than much else. And Chalmers being a PhD.. big deal. I interview one at least every 6 months and have been for about 10 years. I have probably hired four and kept one. An academic qualification does not automagically translate into real world capability. But, this post wasn't about Jim Chalmers. I have a lot of respect for him. It was about general government (including public service) incompetence - or maybe hubris - and how it leads to unintended consequences.. And how a decision in the interest in consumers - in this case hiding fees - may be not actually driven by such altruistic claims. And what does "A business not being able to Pass on a gov't cost is BS. We pass on GST in full. " What in my post does that relate to? BTW, there will probably be a lot of businesses that have had to swallow some of the GST to keep competitive with the big businesses. GST and VAT here work almost exactly the same.. and the hospitality industry especially suffer for it. Sorry if I yet again offended your sensibilities.. I wasn't picking on Labor.. there are plenty of examples on all sides..
-
Jim Chalmers must be feeling its effects today. The "abolition" of credit card surcharges to make the coffee cheaper according to Albo resulted in the ATO scrapping taking credit card payments for tax. I am not sure, but I thought the treasurer would have been consulted before the ATO decided to scrap the ability to pay with a credit card, especially if so many small businesses rely on it - which is in itself a worrying sign. I am trying to work out if this is really unintended consequences or just incompetence. Here is my conspiracy theory. When a consumer is presented a bill at the counter, and they will be slugged a fee for using the credit card, unless they are broke or tempo short of cash on their debit card (assuming they are not going to cop a bigger charge on their debit card use), then they are likely not to use that credit card. That causes a bit of a headache to the credit card companies as that is less lending they are dolling out and less transaction surcharges they are making. So, maybe lobbying the government (and i have no evidence of this), they managed to persuade the government that not allowing credit card surcharges was in the consumer interest. Or maybe consumer groups took the kool-aid and suggested the same to the government - with good intentions. What people forget is that, especially for small businesses - these charges can be 3% + a minimum transaction fee. For small items like a coffee, that can be a bit of change per transaction for the flat fee. But, if a business can't charge a surcharge, they are left with two options: 1. absorb it because all small business owners are greedy bar stewards and want to fleece the public, right? Or two, just pass it on in increased prices - to everyone. But, that way, if you're tempted to use your credit card and avail yourself of the, is it 55 days interest free period, you will do it. The credit card companies still get some money and you're none the wiser. So, Albo spruiking the coffee being cheaper is not quite true and there were stories of before and after prices of the surcharge ban coming in was a biot of an own goal depending on where you purchased your coffee (and other things). Now, the ATO issue. I get that little issue of credit card surcharges on the tax payment may have slipped Chalmer's mind. I mean I am not sure he has had the experience of running a small business and the cash flow issues that come with that. I am not even sure he would have bothered to consult the ATO on the move because the ATO is about tax, and not credit card payments. But, surely, the ATO would have consulted Chalmers before making a unilateral decision to withdraw accepting credit cards if so many small businesses make their payments with credit cards. After all, the ATO just can't raise its prices. In which case, maybe Chalmers forgot to ask how many make the payments and how much is paid using credit cards. I would guess that the ATO would have presented it as, "Gee, boss. If we can't make credit card payment surcharges and unilaterally increase the corporate tax rate, GST, or whatever taxes are paid this way, then we will lose $xbn to the credit card companies." And everyone got fixated on the cost and not the impact. So rather than ask why that would be the case and what would be the impact of going ahead or not introducing a carve out for ATO payments (apart from that being political suicide), the ATO just went ahead - after all - they are a bit of a law unto themselves. Well, it has come to bite the government on the bum. In the scheme of things, not in a huge way, and it will all blow over - The problem is that the decision to allow credit card payments to be taken by the ATO will only be for a year. What then? But, this is an example in poor thinking. The idea that the surcharge would be a boon for consumers is a joke. Ye, only 17& of cafes in this case have unilaterally increased their prices - you can bet others will follow suit. Also, you don't, as a consumer get to take advantage of a lower price by not using cheaper forms of payment. How is that a boon for consumers? Yes, you coul argue it punishes those who are skint at the time.. Er.. if you;re skint, shouldn't you be paring back a bit anyway - using a credit card will just make you skinter. And you have just cut off an important cash flow management capability for small businesses. Well done. I used to have a small software reseller in Aus.. I can't recall if it was Westpac or Anz that provided the merchant facilities to take credit cards, but I recall in the contract, I couldn't apply surcharges (well it was worded I couldn't offer discounts to those not using a credit card that wasn't available to those who used credit cards, if I recall correctly). The transaction costs sometimes made a sale unprofitable when competing with the big fellas. I managed to eek out a living from it, but jeepers it was tough. And that was offering support to try and bring in some margin against the big fellas. Almost every consumer is cost conscious - one learns that very quickly despite what the text books say. I put these sorts of government decisions more to incompetence than to unintended consequences - but the latter is usually the result of the former.
-
I was going to ask abut you.. Glad you're still here. @red750 - First, it's good to hear he is well. Maybe you can entice him back by letting him know that the Block User feature works very well? Send him our best, anyway.
-
Let's talk about Artificial Intelligence
Jerry_Atrick replied to old man emu's topic in Science and Technology
God help us. -
It sounds like there has been a recent regulatory change or that there as been some case that has made a decision that has the banks scrambling. Modern systems have a lot of cross referencing to work out anomalies and match data as they try and remove the human element to it. We are implementing a system that assesses such anomalies and can accept a certain tolerance of differences between identification documents or will refer to a staff member for review. If a staff member can't make the leap, they have probably been instructed by an overly zealous risk manager not to accept any differences. This comes down to risk appetite.. We have an appetite that two people with almost identical identification documents where everything else checks out except placement of letters of a name (but they are in the correct sequence) has a 99.9% probability of not happening. Same DoB, address history, contact details, etc. It's going to be very unlikely that a space interspersed in one doc means it is a different perspon - especially with recognised surname prefixes, etc. Re the credit card thing, it is the banks duty to ensure that, when you apply for new credit that you can afford it (they also should be doing periodical reviews on your existing revolving credit - of which a credit card is a revolving credit line). They are on the hook for your debts and if, after you going broke, the client can prove that they could not have afforded it and they disclosed all relevant information, the bank gets a fine to boot (over here, anyway)
-
I banked with Westpac for a short while. Moved to Bank of Melbourne.. who were then taken over by Westpac. It wasn;t long before their crap was imposed on BoM. Left Australia shortly after anyway, so didn't matter in the end.. Returned with Bendigo Bank who seemed much better.. and had most services retail clients and SMEs would need. Sure many others have recommendations - depends on your needs. But, unless you need access to capital markets or wholesale financing, the Big 4 historically are not the best.
-
I don't know whether to put this in the Gripes thread or start a new thread, Grapes. Admittedly, at least while living here, I occasionally had Jacobs Creek reserve varieties, and of course, Wolfie. But I took 6 months off drinking and am now only having the odd tipple, and ensuring I keep it with the growers/winemakers I know. The problem is, in the UK, there are fewer places to get more independent brands. Around here, Majestic, which is a big national chain, something akin to Dan Murphies but not quite on the same scale, has a small selection of Aussie wines. The old chains, Odd Bins and Unwins folded under debt mountains, but they had the best selection of Aussie wines.. There are some online order sellers, but given where I am wit the move back, I don't want to amass a collection before going and I don't drink enough to warrant sending all back to where it came from. I tried Jam Shed and 19 Crimes and between them, one of them gets. IMHO, the worst wine I have ever tasted and the other a close second.. And I have had a terrible tasting wine.
-
Agree.. But does someone have his email address and can give him a buzz to see.
-
I didn't know whether to sad or funny emoticon that one. Hope the latter
-
Most people knew he was bent when they voted him in. For some reason they didn't care then and I doubt they would care now... if they changed their minds about him, I bet that isn't a factor
-
Bloody typical. Beautiful morning.. forecast was a small chance of rain.. go and buy weedkiller and the moment I step out of the garden centre, it rains... reasonably heavily as well.
-
I was going to say Lycoming, but thought it would be too much of a "dad joke".
-
Content and Providers Worth Sharing(Not Political)
Jerry_Atrick replied to Jerry_Atrick's topic in General Discussion
I love this vid: I just saw this today. I have never met the fella, but a long time ago, I was on the end of a little critique of his for some networking code I developed for Linux. I took it in my stride and sorted out the "shortcomings" in my code, which was adopted into I think it was release 0.94 of the kernel. In all honestly, he is a little narcissistic, but in a good way. -
The fact it is still on the market means it is overpriced. I follow a few Aussie real estate and commercial real estate sites, and this popped up on those about a month ago. One I am looking at a few "doors down" has been on for a long while@ https://www.realestate.com.au/property-residential+land-nsw-tocumwal-203580220 Any of these properties on for more than a few weeks is overpriced. There is also a new subdivision on the airfield: https://www.realestate.com.au/property-residential+land-nsw-tocumwal-204059628 Geelong is a lovely place. I bought my laptop in Geelong in my last trip and the centre of the city has really been freshened up. I am not sure Octave would want me close to him 😉 And, although Ford has gone, the old factory looks fantastic and has a hotbed of tech startups. Tocumwal gets hot - I have spent many a summer for long times gliding there with my terry-towel hat on. But the heat is, by Melbourne standards, dry and very bearable.. As a young bloke, I much preferred the cold, but as I get older, I enjoy the heat much more. But one of the drawbacks is of course, it is a bloody long way from the coast.
-
Yes.. I quite like this shed (though a bit out of my league): https://www.realestate.com.au/property-warehouse-nsw-tocumwal-151477276
-
Let's talk about Artificial Intelligence
Jerry_Atrick replied to old man emu's topic in Science and Technology
Or idiots and crazy -
Yep.. My point was chains seem expensive compared to here.
-
I just love how they accuse everyone else of being exactly what they are... Except, they are also hypocrites.
-
Haven't updated this thread for a while. Most of the structural work has been done. We are fixing up the pointing on the outside of the house as well as the cracks in the cement and stone casings and sis )one of which was letting a lot of water in). That was all done yesterday. In addition, we had to remove a cast iron downpipe that was spit at the read and in a corner so we didn't notice it until it was too late and damp impregnated the walls. Behind it was pointing that was more like syrup, so that had to be removed and repointed. We are waiting a new cast iron downpipe (Grade 2 listed houses - can't replace with decent looking plastic stuff). I think I mentioned on another thread, the day I arrived back in Aus while back at the office (as it is closer to Heathrow, has great showers, etc), I got a call from the partney requesting me to get the sparky in for a power cut. That ended up with a rewire of the whole basement at what turned out in the end to be £5K (or close enough). Ouch... On the interior, we have had the downstairs boot room and dunny done; the living room done (except for the bay, where the new plaster doesn't seem to have been mixed properly and is flaking away.. so waiting for the plasterers to come back and fix it). We actually did the living room in a hurry for Christmas, so it needs some tidying up, but is passable. Same with the formal dining room.. although the fire surround and mantelpiece turned out to be black marble that was painted over, so we are painstakingly removing the paint. You wouldn't read about it. The study is now done (bar painting the segment of the wall that is damp from the leaking downpipe - which we are waiting to dry and using a dehumidifier to help). So, I have moved my desk and slowly moving by home office in there. It is lovely and affords a nice view to the village. Although the kitchen was done long ago, there have been cracks in the plaster (expected) and there was some outstanding painting. That is being worked on at the same time. The basement hallway is painted, which was a pain as we had all new pipe encasement boxes. We have opened iup the downstairs utility room and save for putting curtains (I have no idea why SWMBO wants them rather than doors) on the long sink unit, only the tiling is required. I will get some time on the weekend and try and put together before and after pictures.. Not promising anything as have a lot on this weekend. We are starting the clear out.. The place is full of stuff we have accumulated over the years and don't need. There will be tip runs and facebook marketplace listings. We have decided to go brutal as neither are wanting to move into a big house anymore. They are lovely, but f! they are a lot of work and expensive.
-
Well.. Not really... To be honest, in my case, it would be a godsend. Not a large enough payout to be life changing, but enough to buy me a good chunk of time to work on the property and get going myself. Time for me at the moment is precious - I have not much left over between work and some domestic items that have to be attended to. As I am 6 years at the firm, it would free up some time for me to get stuck in as well.. most of what has to be done now I can do; so it would be a life raft in the move back to Aus, which is now about a decade in the making. (And I know for some, they are thinking long may that continue ;-))
-
I wonder if this makes payment optional?

-
Same..